How to Use Sinking Funds to Prepare for Non-Monthly Recurring Expenses
Marcus Sterling
Senior Loan Analyst · Updated October 2026
Marcus Sterling
Senior Loan Analyst · Updated October 2026
Imagine it is mid-October 2026, and you are enjoying a quiet Tuesday evening when your car suddenly makes a loud, grinding noise. You take it to the mechanic, only to find out that you need new brake pads and rotors immediately. The estimate? $850. Even if you have been diligent about your monthly budget and managed to pay every utility bill on time, this sudden expense feels like a punch to the gut. This is because most standard budgets are designed for 'monthly' life—rent, groceries, internet—but they fail to account for the 'lumpy' expenses that occur only once or twice a year. These irregular costs are the primary reason many people feel as though they are living paycheck to paycheck despite having a stable income.
In this guide, we will explore how you can use sinking funds to transform these financial shocks into predictable, manageable line items. By setting aside small amounts of money throughout the year for known future costs, you create a buffer that protects your primary savings and prevents high-interest debt cycles. We will dive into the math behind these funds, how they differ from traditional emergency funds, and a specific framework to help you implement this strategy in 2026 without feeling the pinch on your current lifestyle.
Navigating modern financial tools like those provided by NationCash can assist with liquidity when needed, but true financial resilience is built through proactive planning rather than reactive borrowing. It is important to remember that sinking funds are not a substitute for an emergency fund; they serve a very different purpose in a healthy financial ecosystem. By the end of this article, you will have a clear roadmap for identifying your irregular expenses and automating your savings so that when the next 'unexpected' expense arrives, it is already paid for.
The first step to mastering a sinking fund strategy is recognizing that many of your most stressful expenses are not actually 'surprises.' They are simply irregular. Many people mistake these for emergencies, but in financial planning terms, an emergency is something truly unforeseen—like a sudden job loss or a medical crisis. A car inspection that happens every year, or the annual property tax bill, is a predictable event with a known frequency.
In 2026, as inflation and service costs continue to shift, being precise about these costs is more important than ever. To identify your targets, you should perform a deep dive into your last twelve months of bank statements. Look for any transaction that does not occur every single month. Common culprits include:
Sinking funds work because they break down large, intimidating numbers into small, digestible monthly contributions. When you look at a $2,400 holiday spending goal as a single lump sum in December, it feels impossible to manage. However, when you view it through the lens of math, the reality becomes much more manageable. The formula is simple: (Total Estimated Cost) divided by (Number of Months until Payment).
Let's look at three real-world mathematical applications for 2026:
A common mistake in personal finance is conflating sinking funds with emergency funds. While both involve setting money aside, they serve distinct roles in your financial architecture. Understanding this distinction is vital to maintaining a stable budget and ensuring you have liquidity when it matters most.
An Emergency Fund is for the 'unknown unknowns.' These are life-altering events that occur without warning: an unexpected medical emergency, a sudden job loss, or a major home repair like a burst pipe. The goal of an emergency fund is to provide a safety net that prevents you from going into debt during a crisis.
A Sinking Fund is for the 'known unknowns.' These are events you know will happen eventually, but you don't know exactly which month they will occur or how much the specific cost might vary. You know your car needs tires; you know you have a birthday in June; you know the property tax bill comes in October.
| Feature | Emergency Fund | Sinking Fund | | :--- | :--- | :--- | | Purpose | Crisis protection | Planned irregular expenses | | Predictability | Unpredictable | Predictable timing | | Usage | Life-altering events | Maintenance/Seasonal costs |
If you use your emergency fund to pay for a planned holiday trip, you are effectively stripping away your protection against real catastrophes. Conversely, if you treat a sinking fund as an emergency fund, you may find yourself 'short' on cash when it comes time to pay for that predictable annual insurance premium.
Building a system of sinking funds does not require a degree in accounting; it requires a structured approach. You can implement this framework starting today to stabilize your cash flow for the remainder of 2026.
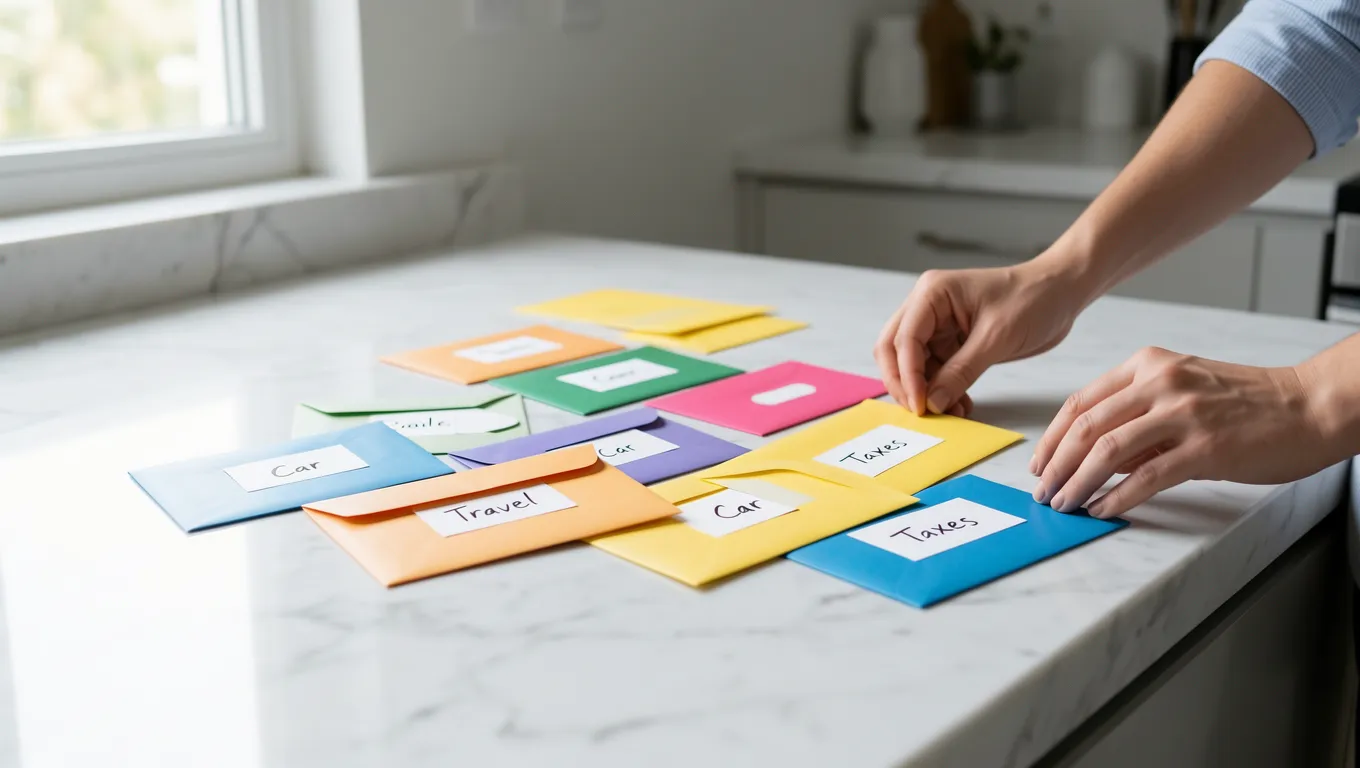
Step 1: The Audit. Review your bank statements from the last year. Categorize every expense that was not a monthly recurring bill (like rent or utilities). This is your master list of 'lumpy' expenses.
Step 2: The Estimation. For each item on your list, estimate the cost. Since prices fluctuate, always aim slightly higher than you think you will need. If car maintenance usually costs <$500>, budget for <$600> to create a small buffer.
Step 3: The Calculation. Use the math we discussed earlier to determine your monthly contribution. Divide that annual estimate by 12 (or whatever number of months you have before the expense is due).
Step 4: The Automation. This is the most critical step. Do not rely on your willpower to 'remember' to save this money each month. Instead, set up an automatic transfer from your checking account to a dedicated savings account on the same day you get paid.
Warning: If you do not automate these transfers, you will likely treat the extra cash in your checking account as disposable income, which defeats the entire purpose of the sinking fund strategy. By removing the decision-making process from your monthly routine, you remove the opportunity for human error and impulse spending.
While the basic framework is effective, advanced savers use a few nuances to maximize their financial efficiency. In 2026, with the availability of various digital banking tools, you can make your sinking funds work much harder for you than they did in previous decades.
First, consider using a High-Yield Savings Account (HYSA) specifically for your sinking funds. Because these funds are meant to sit there until needed—sometimes for months or even years—they should be earning interest. While the monthly gain on a small car maintenance fund might only be a few dollars, over several different funds and a full year, it can add up to cover a portion of your intended expense.
Second, consider the 'Buffer Nuance.' Some expenses are more volatile than others. For example, utility bills in the winter may vary significantly depending on local weather patterns. Instead of setting a fixed amount for a 'utility sinking fund,' you might want to contribute slightly more during the summer months to build a surplus that covers the spikes in January and February.
Finally, remember that your sinking funds are not static. Life changes. You might get a new pet, or perhaps you decide to plan a larger vacation next year. Review your sinking fund allocations quarterly. If you find you have over-saved in one category (like a holiday fund) but are under-saved in another (like car maintenance), you can adjust your automated transfers accordingly without disrupting your primary budget.
Even with a plan, many people stumble when they begin implementing sinking funds. The most common mistake is 'Fund Creep.' This occurs when you start viewing your sinking fund as an extension of your discretionary spending or 'fun money.'
If you have <$200> in your 'Travel Sinking Fund' and you see a great sale on electronics, it is incredibly tempting to dip into that travel fund. You might tell yourself, 'I will just pay it back next month,' but the reality is that most people never actually replenish those funds. Once you treat sinking funds as a slush fund for impulse buys, they cease to function as a planning tool and instead become another source of financial instability.
Another pitfall is 'Over-Complexity.' While having ten different sinking funds sounds organized, it can be mentally exhausting to track them all. If you find yourself overwhelmed by managing too many accounts or transfers, simplify your categories. You do not need a separate fund for every single item. It is perfectly acceptable—and often more efficient—to have one 'Annual Expenses' fund that covers car maintenance, subscriptions, and professional dues combined.
By keeping your system simple and maintaining strict boundaries between what is 'savings for later' and what is 'spending now,' you ensure that these funds actually serve their intended purpose: providing peace of mind when the unexpected (but predictable) occurs.
Borrowers weighing this choice often look at bad credit loans and personal loans for bad credit as well.